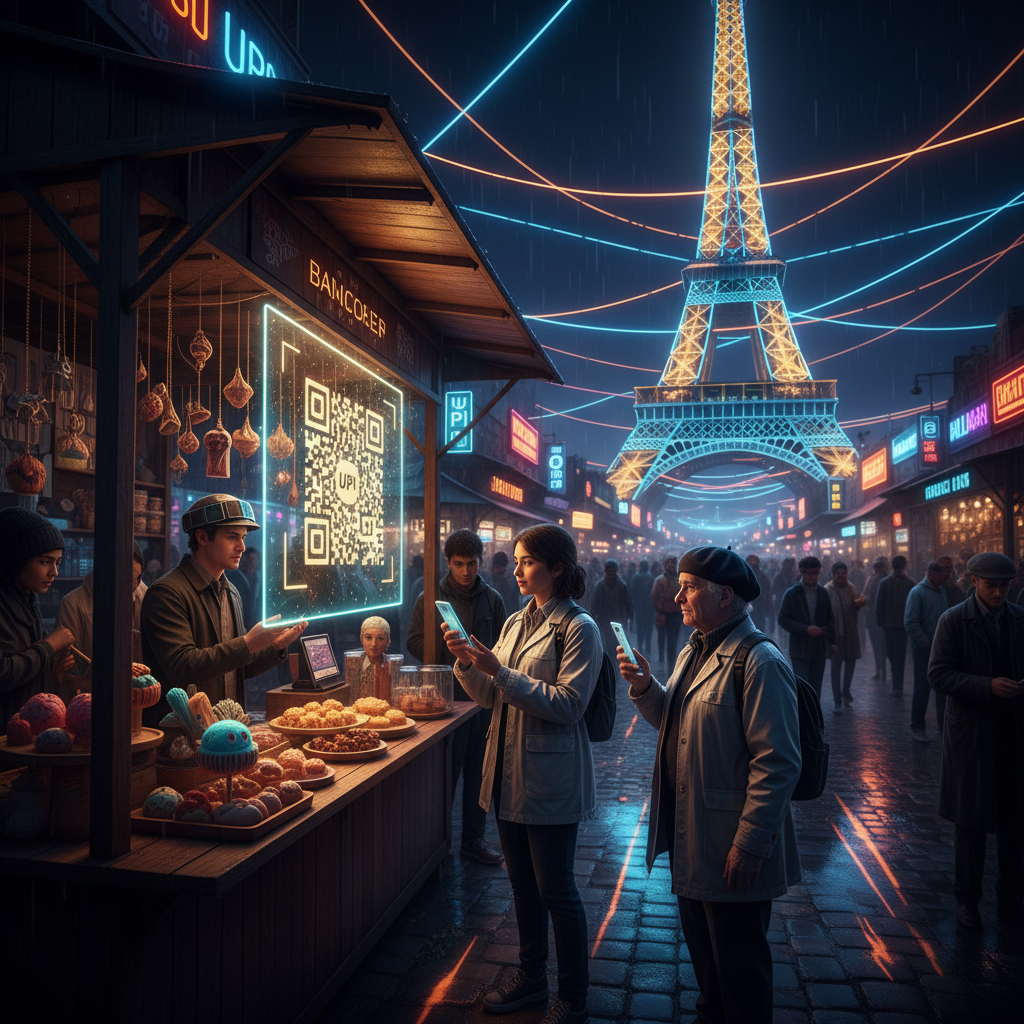
How India’s UPI Became the Global Blueprint for Digital Payments | India Digital Payments System
India's UPI now handles 50% of global real-time payments. Discover the tech and strategy that turned a local QR system into a global fintech icon.

India's UPI now handles 50% of global real-time payments. Discover the tech and strategy that turned a local QR system into a global fintech icon.
Trending Now
How India's UPI Became the Global Blueprint for Digital Payments
Key Takeaways
- UPI recorded 172 billion transactions in 2024 — a 46% year-on-year increase — making it the world's largest real-time payments network.
- By early 2025, UPI's 650 million daily transactions surpassed Visa's global daily average of 639 million.
- UPI now commands 83% of India's total digital payment volume, up from just 34% in 2019.
- The Zero MDR Policy eliminated transaction fees for merchants, accelerating grassroots adoption at an unprecedented scale.
- Over 30 countries are studying or actively adopting UPI-inspired frameworks, powered by NPCI International's global expansion program.
- UPI's success is inseparable from the India Stack — a layered digital public infrastructure combining Aadhaar, eKYC, and open APIs.
In less than a decade, India has engineered one of the most consequential transformations in global financial history. What began as a modest interoperability experiment between Indian banks in 2016 has evolved into the world's dominant India digital payments system — one that now processes more daily transactions than Visa, powers commerce from street vendors in Mumbai to boutiques in Paris, and is being replicated by governments across four continents. This is not a story of luck or market forces alone. It is the story of deliberate policy design, open-source technology, and a billion-person experiment that delivered extraordinary results.
1. The Genesis of UPI: From 2016 Launch to Global Supremacy
The Unified Payments Interface (UPI) was conceived and launched by the National Payments Corporation of India (NPCI) in April 2016, under the stewardship of then-RBI Governor Raghuram Rajan. At its core, UPI was designed to solve a deceptively simple problem: enabling any bank account holder to send and receive money instantly, 24/7, using nothing more than a smartphone and a virtual payment address (VPA).
The timing was strategic. India's demonetization of high-value currency notes in November 2016 — regardless of its broader economic debate — created an acute, immediate demand for digital payment alternatives. UPI was not the cause of digital payments adoption, but it was perfectly positioned to capture the resulting behavioral shift.
By 2019, UPI had grown to represent 34% of India's total digital payment volume, according to Reserve Bank of India (RBI) data. Fast forward to 2024, and that figure stands at 83%, a transformation that reflects not just technological uptake but a wholesale cultural shift in how 1.4 billion people exchange value.
📊 "UPI now accounts for 83% of India's total digital payment volume, up from just 34% in 2019." — Reserve Bank of India (RBI) via IBEF
The full-year 2024 figures are staggering. According to IBEF (India Brand Equity Foundation), UPI recorded 172 billion transactions — a 46% increase in volume compared to 2023. December 2024 alone saw 16.73 billion transactions valued at ₹23.25 trillion (approximately $271.96 billion USD). These are not statistics from a nascent experiment; they represent a mature, dominant financial infrastructure.
2. Decoding the Tech: Why UPI's Open-Source Architecture Won
The architectural genius of UPI lies in what engineers describe as an interoperable, open-loop system built on open-source principles. Unlike closed-loop payment networks such as PayPal's ecosystem or Apple Pay — where the platform controls both the sender and receiver's experience — UPI operates as neutral rails on which hundreds of competing applications can run simultaneously.
The technical stack works as follows:
- Virtual Payment Address (VPA): A user-friendly alias (e.g., name@bankname) that abstracts away complex IFSC codes and account numbers.
- IMPS (Immediate Payment Service): The underlying settlement layer ensuring real-time fund transfer.
- Two-Factor Authentication: Device binding combined with a UPI PIN ensures layered security without friction.
- Open API Framework: Any licensed third-party application — Google Pay, PhonePe, Paytm, or a bank's own app — can access UPI rails through standardized APIs.
This open architecture created what economists call a platform with network effects without platform monopoly. Google Pay, PhonePe, and Amazon Pay all compete vigorously for market share, but none can lock users into their ecosystem. A PhonePe user can pay a Google Pay merchant without friction. This interoperability — absent in most Western digital payment systems — is the foundational reason UPI scaled faster than any comparable system in history.
The approach also dramatically lowered the cost of innovation. Startups did not need to build payment infrastructure from scratch; they could build experiences on top of proven, government-maintained rails. This catalyzed India's broader Fintech Innovation India ecosystem, making Mumbai and Bengaluru among the world's most vibrant fintech hubs.
3. The Zero-MDR Miracle: How India Killed Transaction Fees to Drive Adoption
Perhaps the single boldest policy decision in UPI's history was the implementation of the Zero MDR (Merchant Discount Rate) Policy in January 2020. MDR is the fee that merchants typically pay to payment processors for every digital transaction — globally ranging from 0.5% to 3% of transaction value.
India eliminated it entirely for UPI and RuPay transactions.
The implications were profound. A roadside chai vendor in Varanasi and a luxury retailer in Delhi's Connaught Place suddenly faced identical economics: zero cost to accept digital payments. The traditional barrier of "digital payments are for big businesses" evaporated overnight.
Critics questioned sustainability — who pays for the infrastructure? The Indian government addressed this through budgetary allocations for payment infrastructure incentives, treating digital payment rails as public utility infrastructure rather than a commercial service. This philosophical reframing — that payments infrastructure belongs in the same category as roads and electricity — is arguably UPI's most exportable intellectual contribution.
4. UPI vs. The World: India's Digital Payments Model Compared
How does UPI stack up against the world's other prominent real-time payment systems? The comparison reveals not just differences in scale, but fundamental differences in design philosophy.
Table 1: UPI vs. Pix (Brazil) vs. FedNow (USA) — Core Comparison
| Feature | UPI (India) | Pix (Brazil) | FedNow (USA) |
|---|---|---|---|
| Launch Year | 2016 | 2020 | 2023 |
| Annual Transactions (2024) | 172 billion | ~42 billion | ~85 million |
| Transaction Fee for Users | Zero | Zero | Variable |
| MDR for Merchants | Zero (by policy) | Low (competitive) | Negotiated |
| Operating Model | Open-loop, multi-app | Centralized (BCB) | Bank-to-bank rails |
| Governing Body | NPCI (quasi-private) | Banco Central do Brasil | US Federal Reserve |
| Cross-border Live | Yes (10+ countries) | Pilot stage | No |
| Interoperability | Full (across all apps) | Full | Limited |
Table 2: UPI Growth Trajectory vs. Global Benchmarks
| Metric | UPI (India) | Global Benchmark |
|---|---|---|
| Daily Transactions (Early 2025) | 650 million | Visa: 639 million/day |
| Market Share in Domestic Digital Payments | 83% | — |
| Year-on-Year Growth (H2 2024) | 42% | Global avg: ~8-12% |
| Countries with UPI Acceptance | 10+ | — |
| Registered Users (Estimated 2024) | 300+ million | — |
📊 "In early 2025, UPI daily transactions reached 650 million, surpassing Visa's daily average of 639 million." — IMF / ABC Live
Brazil's Pix deserves special recognition as the world's second most successful real-time payments system. Launched in 2020 and mandated by the Banco Central do Brasil, Pix achieved rapid adoption through regulatory compulsion — major financial institutions were required to participate. UPI, by contrast, achieved comparable dominance through a combination of open architecture, zero-cost incentives, and organic network effects — a distinction that makes India's model arguably more replicable for developing economies that cannot mandate participation.
The FedNow system, launched by the US Federal Reserve in 2023, is promising but nascent. Its adoption remains slow due to America's highly fragmented banking system and the dominance of entrenched private networks like Zelle, Venmo, and the ACH network. The US case, paradoxically, illustrates that advanced economies with legacy financial infrastructure often face greater friction in modernization than emerging economies building on greenfield foundations.
5. The 'India Stack' Philosophy: Public Infrastructure as a Private Innovation Catalyst
UPI does not exist in isolation. It is the payments layer of a larger architecture known as the India Stack — a suite of open APIs built on three foundational pillars:
- Aadhaar: The world's largest biometric identity database, covering 1.3+ billion individuals.
- eKYC & DigiLocker: Digital identity verification and document storage, enabling instant, paperless onboarding.
- UPI: The payments layer enabling value transfer across the full financial ecosystem.
The Digital Public Infrastructure (DPI) philosophy embedded in India Stack represents a paradigm shift in how governments think about technology. Rather than building closed government portals or ceding infrastructure entirely to private actors, India chose a third path: government-built, open-source, open-access public rails on which private enterprise competes and innovates.
This philosophy is now being actively championed by the United Nations, the World Bank, and the IMF as a template for digital development. The concept of DPI has moved from Indian policy corridors to G20 summit agendas — a remarkable journey for a framework conceived in a developing economy.
6. Global Footprint: Tracking UPI's Expansion from Singapore to the Eiffel Tower
The international expansion of UPI, managed through NPCI International (NIPL), is among the most aggressive programs in global payments history. As of 2025, UPI is live or in advanced deployment across more than 10 countries, including:
- Singapore (via PayNow-UPI linkage — the world's first cross-border P2P real-time payment link)
- UAE, Bahrain, Oman, Qatar (critical for India's large diaspora remittance flows)
- France (select merchants, including near the Eiffel Tower — a symbolic milestone)
- Nepal, Bhutan, Sri Lanka (full merchant acceptance)
- Mauritius, Malaysia (in deployment)
The cross-border payments potential is enormous. India receives the world's largest remittance inflows — over $120 billion in 2023, according to World Bank data. Integrating UPI into cross-border corridors directly challenges the dominance of SWIFT-based correspondent banking and intermediaries like Western Union and MoneyGram, which historically extracted significant fees from migrant workers.
The Singapore-India PayNow-UPI corridor has already demonstrated sub-60-second international transfers at near-zero marginal cost — a benchmark that traditional banking infrastructure cannot match at scale.
7. Financial Inclusion on a Population Scale: Impact on Small Merchants and Rural India
The true measure of UPI's success is not found in boardrooms or in trading volumes alone — it is found in the 150 million small merchants across India who now accept digital payments through a QR code printed on a ₹5 piece of paper.
UPI has been transformative for financial inclusion precisely because its barriers to entry are nearly non-existent:
- No POS terminal required — a static QR code suffices
- No bank charges for merchants (Zero MDR)
- Feature phone compatibility through UPI Lite and USSD (*99# banking)
- Vernacular language support across 13 Indian languages
Table 3: Financial Inclusion Impact Metrics
| Indicator | Pre-UPI (2015) | 2024 |
|---|---|---|
| Banked Population (Adults) | ~53% | ~80%+ |
| Digital Payment Users (Estimated) | ~50 million | ~300+ million |
| Merchant QR Code Acceptance Points | Negligible | ~50 million+ |
| Women in Digital Payments (Approx.) | Low (<20%) | Growing significantly |
Critically, each unit of growth carries macroeconomic weight. Research published via Medium's Economics of Everything finds that every 1% increase in UPI transaction volume is strongly correlated to a 0.03% increase in India's GDP — a figure that, at India's current transaction scale, translates into billions of dollars of incremental economic activity.
8. The Credit Revolution: Linking Credit Lines and RuPay to UPI
UPI's next evolutionary leap is the Credit Line on UPI initiative, launched in 2023. This innovation allows pre-sanctioned credit from banks to be directly linked to UPI for real-time disbursement — effectively transforming UPI from a debit-based transfer system into a full-spectrum credit delivery mechanism.
Combined with the RuPay credit card on UPI (enabling credit card transactions via QR codes and UPI apps), India is building what financial analysts describe as the world's most sophisticated credit-to-commerce pipeline for the mass market.
The implications for Fintech Innovation India are profound. Lending startups, Buy Now Pay Later (BNPL) platforms, and neo-banks can now embed credit products directly into the UPI transaction flow — reaching customers who would never visit a bank branch but transact on UPI multiple times daily. This is frictionless credit distribution at population scale.
9. Challenges in the Global Leap: Navigating Regulation and Geopolitics
UPI's international expansion is not without friction. Several structural challenges warrant honest assessment:
Regulatory Heterogeneity: Every country has distinct payment regulations, data localization laws, and licensing requirements. What works under India's regulatory sandbox requires substantial adaptation for jurisdictions governed by GDPR in Europe or the BSP framework in the Philippines.
Geopolitical Sensitivities: Some nations are cautious about adopting infrastructure governed by an Indian quasi-government entity (NPCI). The perception of digital sovereignty risk — dependence on foreign payment rails — has slowed adoption in certain markets that might otherwise benefit significantly.
Market Concentration at Home: The domestic UPI market is increasingly dominated by PhonePe (~48%) and Google Pay (~37%), raising concerns about duopoly dynamics on nominally open rails. The NPCI has discussed market share caps, highlighting the tension between network effects and competitive balance.
Fraud and Cyber Risk: As transaction volumes scale exponentially, so do attempted fraud vectors. While UPI's two-factor authentication is robust, social engineering attacks targeting less digitally literate users remain a persistent concern.
10. The Future of Money: AI, Voice Payments, and Digital Sovereignty
The next chapter of UPI's evolution is being written at the intersection of artificial intelligence, offline capability, and sovereign digital identity.
UPI Lite X enables offline peer-to-peer transactions using Near Field Communication (NFC) technology — critical for areas with intermittent connectivity and a genuine step toward universal access. Voice-activated UPI payments in regional languages are in active testing, promising to onboard India's non-smartphone users at scale.
On the AI frontier, Indian fintechs are deploying machine learning models on UPI transaction data — with user consent — to build alternative credit scoring models for the ~190 million Indians who remain credit-invisible. The granularity of UPI data (frequency, merchant category, transaction timing) provides a far richer behavioral signal than traditional credit bureau data.
At the geopolitical level, India is actively positioning UPI as a soft power instrument — a non-Western alternative to Visa/Mastercard's duopoly and a counterpoint to China's digital yuan (e-CNY) in the race to define the architecture of global digital commerce. The G20 Digital Economy Working Group's endorsement of India's DPI model during India's 2023 presidency was a significant diplomatic validation.
11. Conclusion: Why UPI Is India's Greatest Tech Export and the Future of the India Digital Payments System
The story of UPI defies the conventional narrative of financial innovation — that breakthrough systems emerge from Silicon Valley boardrooms or Wall Street trading floors. Instead, it emerged from a government agency in Mumbai, designed for a billion people who needed affordable, instant, and inclusive access to digital money.
What makes the India digital payments system genuinely extraordinary is not merely its scale — though 172 billion transactions in 2024 and 650 million daily transactions surpassing Visa are figures that speak loudly. What is truly extraordinary is the philosophy embedded in its architecture: that foundational financial infrastructure should be a public good, that interoperability serves citizens better than platform lock-in, and that the fastest path to financial inclusion is removing cost barriers entirely.
As countries from Latin America to Southeast Asia study UPI's blueprint, as the World Bank enshrines DPI in its development frameworks, and as NPCI International expands UPI's global footprint corridor by corridor, India has achieved something rare in the modern era: a technology export born not from commercial ambition but from policy vision.
The world is not merely watching India's payments revolution. It is copying it — and that may be the highest form of global validation.
Sources
- IBEF — UPI Transactions Surged to a Record 16.73 Billion in December
- IBEF — UPI Dominates Digital Payments, Sees Explosive Growth Over Five Years
- NPCI International (NIPL) — Official Website
- Reserve Bank of India (RBI) — Official Website
- Economic Times Government — UPI Transactions Surge 42% in H2 2024
- ABC Live — How UPI Became World's Biggest Payment System
- Medium — India's Rise to Number 1 in Digital Payments
Published on Voxora — Authoritative insights for a connected world.
Advertisement
Frequently Asked Questions
What is the monthly transaction volume of UPI as of 2024?
As of mid-2024, UPI processes over 13.9 billion transactions per month, representing a 57% year-on-year growth. It currently facilitates over 450 million unique monthly users across India.
Which countries have officially adopted or integrated India's UPI technology?
Over 7 nations including Singapore, UAE, Mauritius, Nepal, Bhutan, Sri Lanka, and France have integrated UPI for cross-border payments. Additionally, countries like Japan and several in the Middle East are in active discussions to implement similar technology stacks.
What was the total value of transactions processed by UPI in the fiscal year 2023-24?
UPI processed a record transaction value of approximately $2.4 trillion (INR 200 trillion) in FY 2023-24. This volume highlights its dominance, accounting for over 80% of all digital retail payments in India.
How does the cost of UPI compare to global card networks like Visa and Mastercard?
While global card networks typically charge a Merchant Discount Rate (MDR) of 2% to 3% per transaction, UPI operates on a Zero-MDR model for most transactions, supported by government subsidies to banks totaling over $300 million annually to maintain the infrastructure.
What makes UPI unique compared to other global real-time payment systems?
UPI is built on an open-source API architecture that allows complete interoperability between competing apps like PhonePe, Google Pay, and BHIM. It uses a Virtual Payment Address (VPA), eliminating the need for users to share sensitive bank account details or IFSC codes during a transaction.
Sponsored
Curious about technology, mathematics, education, and growth, I write as a learner exploring ideas in innovation, problem-solving, culture, and the questions shaping our world.
You Might Also Like


Advertisement
Comments (0)
Sign in to join the conversation
No comments yet. Be the first to share your thoughts!